Received: 18 March 2016; Revised: 03 March 2017; Accepted: 15 April 2017
STRATEGY OF FINANCIAL INCLUSION
DEVELOPMENT IN INDONESIA
Bedjo Santoso1*
Ahamed Kameel Mydin Meera2
1Faculty of Economics, Islamic University of Sultan Agung, Semarang, Indonesia 2Faculty of Economics and Business, International Islamic University Malaysia Email:*[email protected]; [email protected] ABSTRACT – The objective of financial inclusion (FI) to facilitate people include the poor able to access financial assistances. It is international institution conducted World Bank. Indonesia rate of FI is 32 %, this means 68% of the poor are not touched by any financial services. The average in the world FI is just 50%. FI is very important to Indonesia as the poverty Indonesia is still high (59%). FI movement in Indonesia is just started formally in 2015. Government vision, mission, and concept have been established, however, the model of FI implemented in Indonesia does not develop properly. Currently, the most literature and practices are just partial. The research on geographic and community based is being ignored. Hence, this research aims to develop a suitable model for Indonesia that is very heterogeneous in term of areas, values, traditions, customs, communities, and local wisdom. This research is a qualitative approach by conducting an interview with the stakeholders. A deductive method is used to explore and to design the proposed model. Besides that, the research employs IDC approach to design the framework. IDC includes intelligence, design, and choice. The result offered three scenarios; the appropriate model is community-based, then, a standard global model of FI, and finally, mobile payment system based on gold as a measurement of value. The using of ICT is possible, it is because ICT has been recently developed into a digital sustainable collaborative networking (DCN) platform, and it is expected to be capable of demonstrating the building of social and economic welfare, particularly in crafting innovations to facilitate marginal society. Moreover, by accommodating the community model which is implemented together with the two models will strengthen to national unity. Keywords: Financial Inclusion, Islamic Value, Local Wisdom, Unbanked Poor People, Community, Mobile System. ABSTRAK – Strategi Pembangunan Inklusi Keuangan di Indonesia. Inklusi keuangan adalah gerakan global dibawah program World Bank untuk membuat orang miskin mampu mengakses layanan keuangan. Tinkat pencapaian inklusi keuangan di Indonesia mencapai 32 %, ini berarti 68% orang miskin tidak terjangkau oleh layanan keuangan sedangkan rata-rata di dunia hanya 50%. Selain itu, angka kemiskinan di Indonesia adalah 59%. Oleh karena itu, Inklusi Keuangan sangat mendesak bagi Indonesia untuk mengatasi masalah ini. Sementara itu, di Indonesia, hal tersebut baru dimulai dengan mengadopsi sistem pembayaran mobile, konsep visi dan misi telah diatur oleh pemerintah. Saat ini, sebagian besar literatur dan praktek berjalan parsial. Sedangkan penelitian tentang geografis dan berdasarkan masyarakat diabaikan. Oleh karena itu, penelitian ini bertujuan untuk mengakomodasi spesialisasi Indonesia yang sangat heterogen dalam hal daerah, nilai-nilai, tradisi, adat, masyarakat, dan kearifan lokal. Penelitian ini adalah pendekatan kualitatif dengan melakukan wawancara kepada para pemangku kepentingan, metode deduktif digunakan untuk mengeksplorasi dan merancang model yang Nilai Islam.
BACKGROUND
The objective of financial inclusion (FI) movement is to aim help all people incude the poor have access to all financial assistances. FI encourages to increase the distribution of service reach to rural areas (Supartoyo and Kasmiati, 2013). Financial inclusion strategy is urgent for Indonesia as FI level in Indonesia is 32%. It indicates that 68% of people are not touched by financial services (Mulya E.S., 2012), whereas Financial exclusion world level average only 55.14% (McKinsey, 2010). Disha Bhanot, et.al. (2012) stressed that the poor to be excluded because of some reasons price exclusion, condition exclusion, marketing exclusion, and self exclusion.
Generally, the objectives of FI more focuse to serve the poor to connect financial access, in this regard McKinsey (2010), Chiba (2009), Radcliffe and Rodger (2012) proposed:
1. The whole part in the society have same opportunity to access FI onthe financial institutions in order especially the poor can be able to improve their standard of living.
2. FI has the potential to stimulate social, economic activity and improve the overall quality of life of their citizens and to serve for financial literacy that is an ability to employ power, skills, and knowledge to manage financial resources effectively for social-economic welfare continuously.
3. FI could be used to develop products to meet customers’ needs, cash flow, risk profiles, fee-for-service offerings, and smaller-unit transactions.
4. FI facilitates the economy digital efficiently by connecting large numbers of poor people to one another, government, financial services, providers, and businesses.
The special objective for Indonesian FI is primarily focused on poverty alleviation as the poverty scale reached to 11.767% (BPS, 2014). It is therefore, financial assistance and empowerment the poor by increasing their capability in business sector through MSMEs in the frame of FI strategy. Some cases, many of unbankable people and MSMEs have difficulties to get formal financial services, it is because they have problems to meet the standard, mechanism and procedure to fulfill it. To deal with this problem, some experts proposed by using ICT and mobile phone payment system i.e. Moorthiet et.al. (in Supartoyo and Kasmiati, 2013) suggested using mobile phone in form of branchless banking system. These sugestions based on assumption that even poor, they have mobile services.
In order to accelerate implementation process FI, government must actively contribute in solving those problems (Gerai Info, 2011). Indonesian President gave his commitment for FI program, as he said in G-20-AFI summit in 2012 that “….financial inclusion is going to be national agenda to tackle poverty issue in Indonesia”. Furthermore, Darmin Nasution, former Governor of Indonesian Central Bank (BI) said that financial inclusion has became the main program to decrease economic discrepancy that began in 2010. Moreover, Hadad, former Head of Indonesian Financial Authority (OJK), said that government is ready to implement financial inclusion to reach unbanked people in order financial services have to be available for everyone including poor people. In addition, Mulya E Siregar, BI’s R&D Director, said that financial inclusion has become national issue to strengthen nationalism value.
Then the question is what method to be used in Indonesia to develop FI, because there is no any guidances to develop FI, some exixting model are top downs, bottom up, and collaborative model. Even, some literature propose FI based on believes, customs, traditional cultural institutions, and cooperative value.
Moreover, a study to explore appropriate FI model in Indonesia is very important by by adopting global FI model or Indonesian special characteristics or combining all altogether. It is therefore, this study try to propose FI that appropriate in Indonesia. Writing systematic of this paper is begining by reading literature of developing FI model in the world, then analyzing the drawback of the existing model in the literature, and then the appropriate model is proposed regarding special characteristics of Indonesia i.e. cultures, institutions, values, customs, local wisdoms, Islamic values and community cohesiveness.
OBJECTIVE OF THE STUDY AND RESEARCH METHOD
Indonesian model of financial Inclusion movement is very important, therefore, the study aims to develop an appropriate FI model in Indonesia which is to focuse some Indonesian characteristic i.e. cultures, religions, communities, and local believe. The study tries to involve the role of ICT for supporting to model. This study is a qualitative method which is based on the topics raised. A deductive method is considered as an appropriate method to deal the problem. This is because it requires a comprehensive discussion on the data collection, data analyses, and deductive conclusion. Then, it will be analyzed to develop an appropriate model. Furthermore, this research also employs primarly, and secondary data, and library data as well. Besides that the current financial inclusion data in the world wide is also collected. Moreover, in-depth interview has been dones to make sure the model is viable.
LITERATURE REVIEW
FI is a movement to encourage financial system services is accessible for all people to strengthen the economic development based on justice and quality as well as to tackle poverty where all issues are in line with Islamic mission to achive welfare and justice in economic life. FI will waive out all obstruction to access financial services include by involving infrastructures, ICT, the aim of the program is to ensure sustainable growth and giving benefit to economic and social welfare. Currently, growth of information and communication technology is giving us the chance for providing special financial services to most people. Surely, many branchless banking based on mobile money schemes are currently spreading in the world wide. Moreover, these schemes can be sustainable, viable in the next decade if it develops by including all stakeholders in the society, properly concept, and exact regulations. However, the question then how to implement this model in Indonesia which is differ with other countries in the world wide in some cases.
That’s why, the next session we will discuss the existing literature review for our base stand and finding research gap that being neglacted in the existing research. Firstly, the existing research on financial infrastructures, pillars of FI. Secondly, the experience and approach used by several countries on the financial inclusion development. Thirdly, barriers and challengers for Financial Inclusion Development. Then, fouthly, we discuss strategy FI for Indonesia and issteues rised in the current system.
The Role of Pillars in the Financial Inclusion Development
Chiba (2009) introduces that FI has four main pillars; Private sector development (financial and non-financial), financial literacy, microfinance and public sector support. The development of the financial sector is known as a prerequisite for growth and poverty reduction (Hossein and Kirkpatrick, in Chiba (2009). Financial development is very important concerning; Institutional regulation, economic dimension (medium term). In addition, the role of the non-financial private sector is also important for FI development, such as; E-banking and telecommunications, information technology, mobile phones, and poor people’s services to bring to the financial sector
NFER (1992) defines financial literacy as’ the ability to make informed decisions and make effective decisions regarding the use and management of money. The crucial role of financial literacy is evident in field research and related analyzes, particularly in assisting the use of microfinance information, in promoting engagement in the formal financial sector, and in addressing the tradition issues that guide the behavior of many citizens with respect for financial transactions (Chiba, 2009). While IDB (2009) emphasizes financial literacy is seen as ‘the frontier of subsequent training’, especially by donor and multilateral organizations.
Research on the role of microfinance to FI on average concludes that there is no success without microfinance, some of which suggest that microfinance is a key success factor for promoting FI, in some cases providing evidence that microfinance is a very important tool to Facilitate FI through smart smart approach for customers to get people based on trust (Ibrahim & Fitria, 2012). Karlan and Zinman (2007) prove that microfinance provides strong evidence to support the positive role of microfinance in tackling poverty. In addition, Jayati (2013) has conducted a study in the latest literature on microfinance in developing countries and a critical assessment of its effectiveness in India. The study finds that an important role of the microfinance sector is for a viable FI strategy for the poor and small producers.
The role of public / government sector support has a central role to facilitate FI in terms of legislation and legislation, policies, procedures, programs and mechanisms of accountability. The public sector must involve in political economy, political will, multipartite negotiations, charter, incentives, and monitoring mechanisms. These goods must be authorized by the government in connection with the authority and not enough private sector to take over (Chiba, 2008). Roles also involve initiatives to educate the community, no FI without educational activities. In connection with the Bhave (2014) issue undertaken by research in India, it was established that this activity could reduce the gap between the rich and poor in India by phasing methods until 2019 by educating the public through financial literacy activities. In addition, there are more studies around the role of ICT and branchless and mobile banking in developing countries. Demish, et. al (2011) stipulates that a branchless banking system utilizes more and more long-term business transactions for the living and working poor and the socio-economic impact. Meanwhile, the role of mobile phones has been studied in Africa which concludes that the role of mobile in digital finance in African countries contributes significantly to economic growth as part of its FI strategy (Mihasonirina, 2012). In addition, Sankaramuthukumar and Alamelu (2012) highlighted the relationship between user demand side, financial access strategy, and financial use. He concludes that there is a direct link between financial access strategy and financial use, to increase FI can be achieved by improving four important elements; Comfort, reliability, flexibility and continuity to achieve greater FI in Africa.
From the above description, there are several issues that have not been discussed, most of the literature focused on partial research the role of pillars of FI such as ICT, public sector, microfinance of the financial sector and financial literacy. Research on the geography of FI focusing on the special community as an alternative institution and its relationship with mainstream finance abandoned. In addition, only research that is detected is an important study related to the role of communities for successful FI handled by Fuller and Andrew (2002), basically this research is important for this study which concluded that the role of community economic institutions is very important to do. Combating social and financial exclusion. Basically, this study focuses on the UK’s credit union community outlining the role of community institutions for successful FI.
Furthermore, in this session, it will be analyzed whether the existing literature is suitable for the Indonesian language that has certain heterogeneity criteria involving a wider region of the world and is inhabited by more than 300 million. This can be reviewed as follows:
1. Chiba (2008b), DFID (2004) and Hossein and Kirkpatrick (2005) which results financial sector development is well recognized as being a prerequisite to growth and poverty reduction. Financial and non financial private sector development is very important to serve the poor. The leading pillar on financial and non financial sector.
2. NFER (1992), Chiba (2009) and Atkinson and Messy (2013) on the research which result financial literacy as ‘the ability to make informed judgments and to take effective decisions related to the use and management of money. The important role of financial literacy to enhance people for financial transactions. Financial literacy strategy has significant impact to FI development. The leading pilar on financial literacy.
3. Karlan and Zinman (2007) and Jayati (2013) the research which result Financial literacy as ‘the ability to make informed judgments and to take effective decisions related to the use and management of money. The important role of financial literacy to enhance people for financial transactions. Financial literacy strategy has significant impact to FI development. The leading pillar on microfinance.
4. Chiba (2008) the research which result the role of public sector support / government has central role to facilitate FI in term of regulations and legislation, policies, procedures, programs. The leading pillar on the public sector.
5. Bhave (2014) Educating people on financial literacy activity can reduce the gap between the rich and the poor in India by staging method till 2019. The leading on financial literacy.
6. Demish (2011), Andrianaivo (2012) the research which result Branchless banking systems take advantage of increasingly in term business transactions for poor people live and work and socio-economic impacts. The role of mobile phone in the digital financial in African countries contributed significantly to economic growth. The leading pillar on ICT-Digital Mobile Financial.
7. Sankaramuthukumar et.al (2012) the research which result the direct relationship between financial access strategy and financial usage, to increase FI can be achieved by increasing; convenience, reliability, flexibility and continuity in African countries. The leading pillar on Financial strategy.
Financial Inclusion Development Strategy in the World Wide
In fact, a study by the World Bank (2010) shows the effect of financial exclusion is the allocation of lost resources. Financial assistance does not touch people who are not interested really in need, on the contrary, those who have access to financial excess had more help (McKinsey, 2010). The imbalance situation will be a systemic and sustained outbreak. Hence required a preventive strategy that is FI. FI has begun in 112 countries in the world and only 14 countries are in the maturity stage. However, these countries use a partial approach. A review of 14 countries in terms of approach is as illustrated as folows: (Chiba 2008, 2009; Jayati, 2013)
First, India, The public sector provides the overall framework, FI policy/product guidance from the central bank. Public ector, Cooperatives, Microfinance and ICT are involved. Employ not all pillars. Second, Guatemala; Continental; Banrural and Mexico, Commercial banks offer microfinance services to the unbanked. Cemex as a private sector non-financial firm assisting the FI through a savings and credit scheme for the poor and unbanked people. Private formal financial institution, ICT Provider, Financial sector, Public sector are involved. Employ not all pillars. Third, China, financial literacy in support of effective and efficient microfinance. NGOs to be effective partners for financial literacy and microfinance. Private formal financial institution, ICT Provider, Financial sector, Public sector are involved. Employ not all pillars. Fourth, Philipines, The Globe Telecom Co., Mobile telephone providers offers mobile banking services (bill payment, ‘mobile wallets’, non-bank accounts and cash transfers) – to the banked and unbanked. Telecommunication service firms are providing cost-effective and efficient financial services to the unbanked, including those in remote areas. Private-Non-financial Firm, ICT provider, Central Bank, Financial Sector are involved sector. Employ not all pillars. Fifth, Brazil, Remote and under serviced areas can receive improved access to financial services through private bank collaboration Partnership between private banks and the post office is one effective way to raise up existing infrastructure. Private and Formal financial institution, Communities are involved sectors. Employ not all pillars. Sixth, Mexico, Bank accounts for the unbanked; funds transfer service for remittances from the US to Mexico’s unbanked. This strategic led by central banks to address FI. Public sector and Private Sector are involved. Employ not all pillars. Seventh, Kenya, South Africa, Ghana, Nigeria, Maldives, Columbia and Mongolia and South Africa, Microfinance services and Commercial bank promote FI . Microfinance and financial services to promote entrepreneurs, and serving the ‘unbanked’ people. The role of IFC, World Bank Group, to support FI. Technology – e.g., mobile phones, prepaid cards and electronic kiosks – offers a viable medium for FI. Guidance from the public sector, the formal financial sector developed a Financial Sector Charter (FSC) for FI to serve the poor. Formal financial institution, ICT Provider, Public sector, Private sectors, Financial and non-Financial firms, ICT provider are involved sectors. Employ not all pillars. Eight, Trinidad and Tobago (T&T), The public sector leads Financial Literacy with the central bank as the coordinating agency and with the support of other key stakeholders to support FI. Public sector, financial literacy, NGO’s. Employ not all pillars.
From the description above described 14 cases of FI models in the world. This illustrates the approach of inclusive financial development incompatible with Chiba (2009) which proposes four pillar theories. For the Indonesian model should involve all pillars such as financial literacy, public sector support, government, and political interests, NGOs, Communities, ICT providers, microfinance, the public finance sector, and the private sector. Its approach is better linked to issues of heterogeneity and complex issues of Indonesia.
Barriers and Challengers for Financial Inclusion Development
The development of FI in the world wide has a number of common themes emerge main barriers (Madhur, Jha, et. al., 2014):
Table 1. The Barriers and Challengers of Financial Inclusion Development No Barriers Explanation 1 Natural Such as geographic, distance and culture which barriers affect to model development, heterogeneity of culture and value, difficulties and cost. Besides that, religious concerns over interest payments can also be a challenge to FI too low proportion of adults that are ‘banked people’ (Demirguc-Kunt and Klapper, 2012).
| No Barriers | Explanation |
|---|---|
| 1 Natural Such as geographic, distance and culture which | |
| barriers affect to model development, heterogeneity of | |
| culture and value, difficulties and cost. Besides that, | |
| religious concerns over interest payments can also | |
| be a challenge to FI too low proportion of adults that | |
| are ‘ banked people’ | (Demirguc-Kunt and Klapper, |
| 2012). | |
| 2 Lack of Involves | borrower-lender information access, |
| financial public credit registries, and private credit bureaus, | |
| infrastructure this lack can be tackled by governments play key | |
| role. Besides that, getting credit Strength of legal | |
| rights, depth of credit information, public registry | |
| coverage, and private bureau coverage consider as | |
| factors that influence FI development. | |
| 3 Restrictive The regulations have important role–to protect | |
| regulations consumers and to act as prudential regulators | |
| principally concerned with maintaining the integrity | |
| of individual institutions and of the financial system | |
| as a whole. In other word, they want to limit | |
| exploitation of the poor through unfair contracts, | |
| fraud, excessive prices and interest rates. In this | |
| regard, Kaddu (2014) initiated that national and | |
| international regulatory policies are often cited as |
2 Lack of Involves borrower-lender information access, financial public credit registries, and private credit bureaus, infrastructure this lack can be tackled by governments play key role. Besides that, getting credit Strength of legal rights, depth of credit information, public registry coverage, and private bureau coverage consider as factors that influence FI development.
3 Restrictive The regulations have important role–to protect regulations consumers and to act as prudential regulators principally concerned with maintaining the integrity of individual institutions and of the financial system as a whole. In other word, they want to limit exploitation of the poor through unfair contracts, fraud, excessive prices and interest rates. In this regard, Kaddu (2014) initiated that national and international regulatory policies are often cited as further barriers to broader formal FI for the world’s poorest people. For example at the national level, banks often require individuals to register themselves in order to meet regulations around the prevention of money laundering and to combat the financing of terrorism.
4 Governance The governance failure indicators that which affect failures to FI development are rule of law, regulatory quality, government effectiveness, control of corruption and political stability. While, minimizing corruption and ensuring a stable political environment will mean that better progress can be made towards addressing the key barriers to FI .
5 Products Innovation and creation is the key to perform features attractive financial products. Financial products need to be tailored to meet the needs of the poor.
Products need to be affordable, available within reasonable physical proximity and regulated to protect consumers, differentiation, segmentation, and design features strategy are important to have better financial product. Besides that, lack of financial literacy among the poorer segments also represents a significant barrier to the access and proper use of formal financial services.
6 Moreover Blanco et.al. (2014) considered that culture and traditional are the most barriers faced by the FI based on community. However, these obstacles also present as the greater opportunities (Blanco et.al.
2014). Moreover, Sankar (2013) postulated that psychological and cultural barriers also cause to negative FI in India, besides, physical barrier stemming from distance to bank branch or automated teller machine (ATM).
From the table above, it can be concluded six constraints of development of FI, and this is considered as a criterion f or evaluating the proposed model. The obstacles are: geographical and distance factors, physical infrastructure and facilities, national and global financial regulations, governance failures, product and service features, cultural and religious values.
Alliance Financial Inclusion (AFI)
AFI initiated by Bill&Melinda Gates Foundatio and support by World Bank which is facilitating their members to share and implement their information of policies that the increase access to financial services for the poor. AFI activities involve several types of financial inclusion action, such as; working groups, a membership program, grants, and peer exchange platforms such as yearly global policy forum. AFI membership is open to any financial inclusion including central banks and other financial regulatory institutions. Eighty developing countries have been registered as members where the majority is the world’s unbanked.
The AFI movement earn prize very enthusiastic, 108 countries joint as members. They conducted Annual Global Policy Forum (GPF). GFC is a strategic forum to optimize impacts on development by enhancing the arrangement of financial inclusion, financial stability and consumer protection objectives. GPF conference also was attended by 100 central bankers and financial policy makers from developing nations that concern to improve their financial ability. The development of Alliance Financial Inclusion (AFI).
Some Issues Raised to the Financial Inclusion Development in Indonesia
The specialty of Indonesia in term wide range area, number of ethnics, cultures, value and traditional value, and religions as it was discussed as above; it is therefore, need specific design which encourages a comprehensive approach and strategy. Combining top-down and bottom-up for establishing FI is considerably necessary. In this regard, the writing issues related to the development of FI s in Indonesia, firstly, the positive and externalities factors as a positive influence including the government and other formal financial institutions, community support and the existence of Cooperatives and NGO’s institutions. Besides, there are many factors that could either hamper or support the financial development in Indonesia, such as the existence of micro financial institution, traditional values and religion institutions, and the financial institution based on other community. These factors can be considered as positive and negative factors.
Several positive externalities which are support to Indonesia FI establishment can be categorized into programs, infrastructures, and institutions. Program and process comprises; government vision, instruments, political climate, and financial sector and private sectors existence. All of the things put Indonesia in secure area as Indonesian President said that FI is going to be national agenda to tackle poverty issue in G20-AFI summit and Global Policy Forum 2012 in Bali and Mexico then followed up by pilot projects development initiated by Indonesian central bank (Bank Indonesia) for attaining FI national program 2015 in all provinces to cover unbanked people (Hadad, 2010) as it can strengthen unity. Moreover, Darmin Nasution (2013) stressed that FI to be priority program to mitigate the income gap. Since 2010 Indonesian Bank has launched the national strategy for FI by prepared a clear vision, mission, and objectives as well as the guidance its implementation for fastening the FI implementation as means to serve unbanked group. Additionally, Indonesian bank has developed a program to change unbanked to be banked people by identifying a client with three stages namely financial identity number (FIN), then to be customer identity number (CIN). Finally, changing a client to be DIN (debt identity number) (Swadiyanti, 2011:4).
In term of micro finance as merchant instrument, Kartiko (2013) as Islamic micro finance activist ensure that micro finance sector ready to synergy in the program. While Rofah (2012) said that people in the society is ready because they have a good characteristic namely, easy for participating in the public development. Some of them obey to cultures value, local wisdom, and religion value such as Islamic value.
Furthermore, Muhammadiyah and Nahdlatul Ulama are the largest mass organization in Indonesia, where the two organizations have 30 million members has been reviewed and ready to implement a mobile payment system that applies to its members for a while by introducing Cooperatives. Besides that, in Indonesia also have so many Cooperatives that owned by NGO’s, mass organizations, Islamic Boarding schools, Catholic and Christians, and government Cooperatives, the organizations are very potential as agents, which have spreaded from provinceuntil rural i.e. Muhammadyah have 5.500 sub districts and Nahdatul Ulama (NU) have 6.000 sub districts in Indonesia that could be as merchants or agents for any transactions settlement. Moreover, al-Wasliytah and Nahdhatul Wathon as well can support the effort, also Cooperatives owned by Catholic i.e. Bhakti Kita and Credit Union. All above will strenghthen FI based on community. Besides that, there are some Isblamic Cooperatives called Baitul Maal waTTanwil (BMT) i.e. Perhimpunan BMT, Sidogiri BMT, and Fastabiq that have wide and closed relationship / network to the society.
In addition, Indonesia also very strong in term of informal local financial institutions which has been grown in some places in the name of local transaction system based on values of cooperation, mutual trust with the main purpose of helping each other. This system covers all community activities such as economic and social, credits, buying and selling, marriage, and other related religious transactions. Moreover, the potency of local wisdom based on religion or culture in term of financial transactions very huge that will strengthen the development of the best model of FI based on culture and value. These potencies are as follows: (The Indonesian Community Currency, 2014)
1. Merapi Mulia community in Yogjakarta which is operated based on Javanese brotherhood to help others by buying-selling, charities, loan, and investment.
2. Banjar-Bali in Bali province, it was based Hindu mutual assistantship values, the transactions trading, planting and fishing.
3. Gerai Dinar movement lies in Jakarta, Surabaya, Semarang, Sumatra that focused on implementing Islamic Gold Dinar adoption for daily transactions i.e. buying-selling, charities, investment.
4. Wakalah Induk Nusantara (WIN) located in Depok, Jakarta, Bandung, Tanjung-Pinang, Cirebon, Ternate based on Islamic Gold Dinar as currency for buying-selling, charities, investment, trading 5. Dinar First in Jogjakarta which operated Islamic Gold Dinar-Dirham for educating, Trading, and Investment.
6. Cooperatives of Bhakti Kita in Middle java, West Java, and East Java based on Catholic, Christians values to assist poor people in term of loan, empowerment, buying-selling, charities, and investment.
7. Baitul Wa Tanwail (BMT) spread in all Indonesian provinces based on Islamic finance principles for grab poor people in term assistances, charities, loan, investment, and business transactions for MSMEs.
8. Tuha Peut, Gampung in Aceh, it is a Local Value based on Brotherhood, communication, assistances, collaborations, and business. It based on from and to members.
Besides the positive argument as it was discussed that support FI which has been built in Indonesia under Alliance Financial Inclusion (AFI) in general, however, there are various debates appeared whether pro and contra to AFI program. The supporting view comes from conventional and Christians micro credit activists. While, the contra argument comes from Islamic micro finance activist such Baitul Maam wa Tanwil (BMT), Cooperatives, and KOPONTREN (Islamic boarding school Cooperative). Moreover, from the Islamic finance activists do agree with some notes. In fact, FI has been developed under supervision World Bank in cooperated with IMF where these institutions contribute to great suffering during Indonesian crisis in 1998. It is therefore, they have some objections and hesitations on the silent-agenda in this program (Awalyl, 2014). These objections can be divided into three aspects: vision-mission, business agenda, and Islamic perspectives. For instances, Mr. Awalyl Rizky, the Vice President of Indonesian Baytul Maal wa Tanwil (BMT) Association and Kartiko Wibowo as Central Java President of Local Micro Finance.
The Differences Alliance Financial Inclusion -AFI (Top Down Model) and
Community -Islamic Value Model (Bottom-Up)
The establishment of FI under AFI has different agenda with bottom-up model which is based on value, mutual assistanceship and collaboration, the differences includes; mission, concept, and principles of Indonesian micro finance development especially Islamic micro finance such BMT. It described in Table 2 as follows:
Tabel. 2. Diffences Alliance Financial Inclusion (AFI) and Community –
Islamic Value Model
No Element Description
a. AFI model has different agenda which Islamic 1 Vision-
Mision microfinance and credit that focus on brotherhood, cooperation, and assistantship.
b. AFI has silent agenda to build a global networking toward micro finance liberalism without any value.
This is opposite with Islamic value (Kartiko, 2014).
c. There are some facts that the most World Bank’s assistance and involvement in Indonesia does not meet to the welfare issue.
d. Some World Bank’s programs make some
difficulties to developing countries.
e. In term of principles Islamic and conventional FI is difference, Islamic value based on gift value, and it does not based on debt principles, if person is not able to give, this person is encouraged to make saving little by little after that to be lenders. While, the common FI program the sense is focus to take benefit by borrowing from FI (Harjono, 2014). a. Credit Cooperatives and Credit Units (Koperasi Program Simpan Pinjam & Unit Simpan Pinjam (KSP/USP) are the agen for financial services to micro small and medium enterprises (MSMEs) which is strategically for the economic growth in the rural.
b. Cooperative developed by mutual assistantship principles and inclusion among them, including 108,000 KSP/USP; this amount is about more than 90% of Indonesian KSP/USP all and covered more than 18 million members include MSMEs. Terefore, they afraid AFI will remove such cultures. FI built by AFI, World Bank, IBRD, and International Financial Corporation (IFC) just focus to business oriented, global networking, mass production that all focused to material value. Whereas BMT focuses to both material and spiritual.
a. Indonesian Baitul Maal wa Tanwil (BMT) is an 3 Islamic value Islamic micro finance agency which serves the principles society based on mutual cooperation, based on trust value. BMT’s aid is based on Islamic financial credit principle such as Qiradh and Syirkah (profit loss sharing) which are encourages in Islamic value. b. BMT declares that it is an Islamic missionary endeavor (Da’wah) institution to serve people toward better life today and hereafter. c. AFI program does not has clear vision to serve the ummah, it just focused on the business motive and interest charging which does not allow in Islam.
a. World Bank, IBRD, and International Financial 4 Business and Corporation (IFC) are giant businesses with global financial networking. Sometimes they employ any strategy to reason force the government by some manner such as regulations involvement, political power, and economic power.
b. The government should protect the domestic industry to compete with global power. Hence, the government should support microcredit micro small medium enterprises (MSMEs) during crisis as they have significant role to the economics resistances. Finally, as above discussed, it can be concluded that the positive and negative factors can be considered as externalities issues to develop FI in Indonesia:
1. FI program under Alliance FI (AFI) is a global financial program hatched by the World Bank in cooperation with Bill Gates Foundation in terms of ICT. Basically, not all programs initiated by the World Bank are accepted by some of Indonesian people. They argue that any world programs cause some domino effects to the social economic. They grant a debt with some rigid requirements that will affect socio-economic life ratio in the future. This group of people tends to be unconcerned and unsupported the program (Awalyl, 2014).
2. AFI program is worried to get a very limited support due to the fact that not all Indonesian people want to deal with banks, even conventional bank because the socio-cultural studies experts say that there are some tribes in Indonesia grudge against the Dutch colonized Indonesia when the oppressive, so they assume that every practice of bank and education is related to Dutch colonized (Raharjo, 2014).
3. The program based on local knowledge needs to stimulate, for the people in Indonesia in business and social transactions, there are some factors built on traditional values that lead to the values of honesty, cooperation and mutual aid based on consensus. Institutional systems of indigenous are referenced by peoples in Sumatra, Kalimantan, Sulawesi, Maluku, Bali, West and East Nusa Tenggara and Irian Jaya i.e. in Aceh which has a value is called Gampong-Tuhapeut value. Generally, the value is based on cooperation, brotherhood, deliberation, and obedience (Damanhuri, 2012). By this value the people to be able build any project based on togetherness and cooperation, besides that, based on this system the people will implement or not implement something before consultation to their Islamic scholars which are very important and decisive in providing guidance, even they are very obedient to them. And this culture is still working and operating in the current system (Abubakar, 2014).
4. The most financial barriers to adoption in the traditional value include the value religion, but it is still not clear how to resolve the issue. For example is in Bali which is called Banjar traditional society with a system based on the Hindu’s value system allows to execute transactions with community treasures. This system is headed by the head of customs and community members obeyed by him.
5. The role of Cooperatives in the community needs to consider because in Indonesia there are Cooperative networks, both formal and informal, this various types of cooperatives such as savings and loans help each other with capital purposes and to cooperate voluntarily. Even, Cooperative has been formed based on sharia, called Baitul mall Wa Tanwil (BMT). This cooperative has a network of grass roots up to the village. In fact, it has a network of services to 50 million people served by the BMT. Hence, based on the above facts, it should be considered as the comparative advantages to develop FI based on Cooperative. Moreover in term of barriers, challenges and externalities, then, we propose two models of the FI development in Indonesia, those are:
1. Top-down general models designed by central government.
2. Community FI Model based on the value of local wisdom, then, these two alternatives will be analyzed by six indicators of barriers which is discussed in the previous session of barriers and FI for development.
ANALYSES OF THE PROPOSED MODEL OF INDONESIAN
FINANCIAL INCLUSION
In this section we will analyze the alternatives model of FI to be implemented in Indonesia by using deductive analysis. Two alternatives offer two alternatives, namely: the top down global model designed by government linked with global finance institution and community FI model based on local value wisdom.
Alternatives Criteria Top down global model
Community Financial No designed by government
linked to global financial (Barriers)
local value wisdom
institution 1 Geographic To address with this issue; To address with this issue; and distance using mobile phone using mobile phone factor (Branchless Banking) (Branchless Banking) * 2 Infrastructures Government should play Government may help to and physical the key role to deal with address with the issue ** facilities the issue and need high budged
Table 3. National and Government should Not involved to the global finance struggle to fulfill the issues***
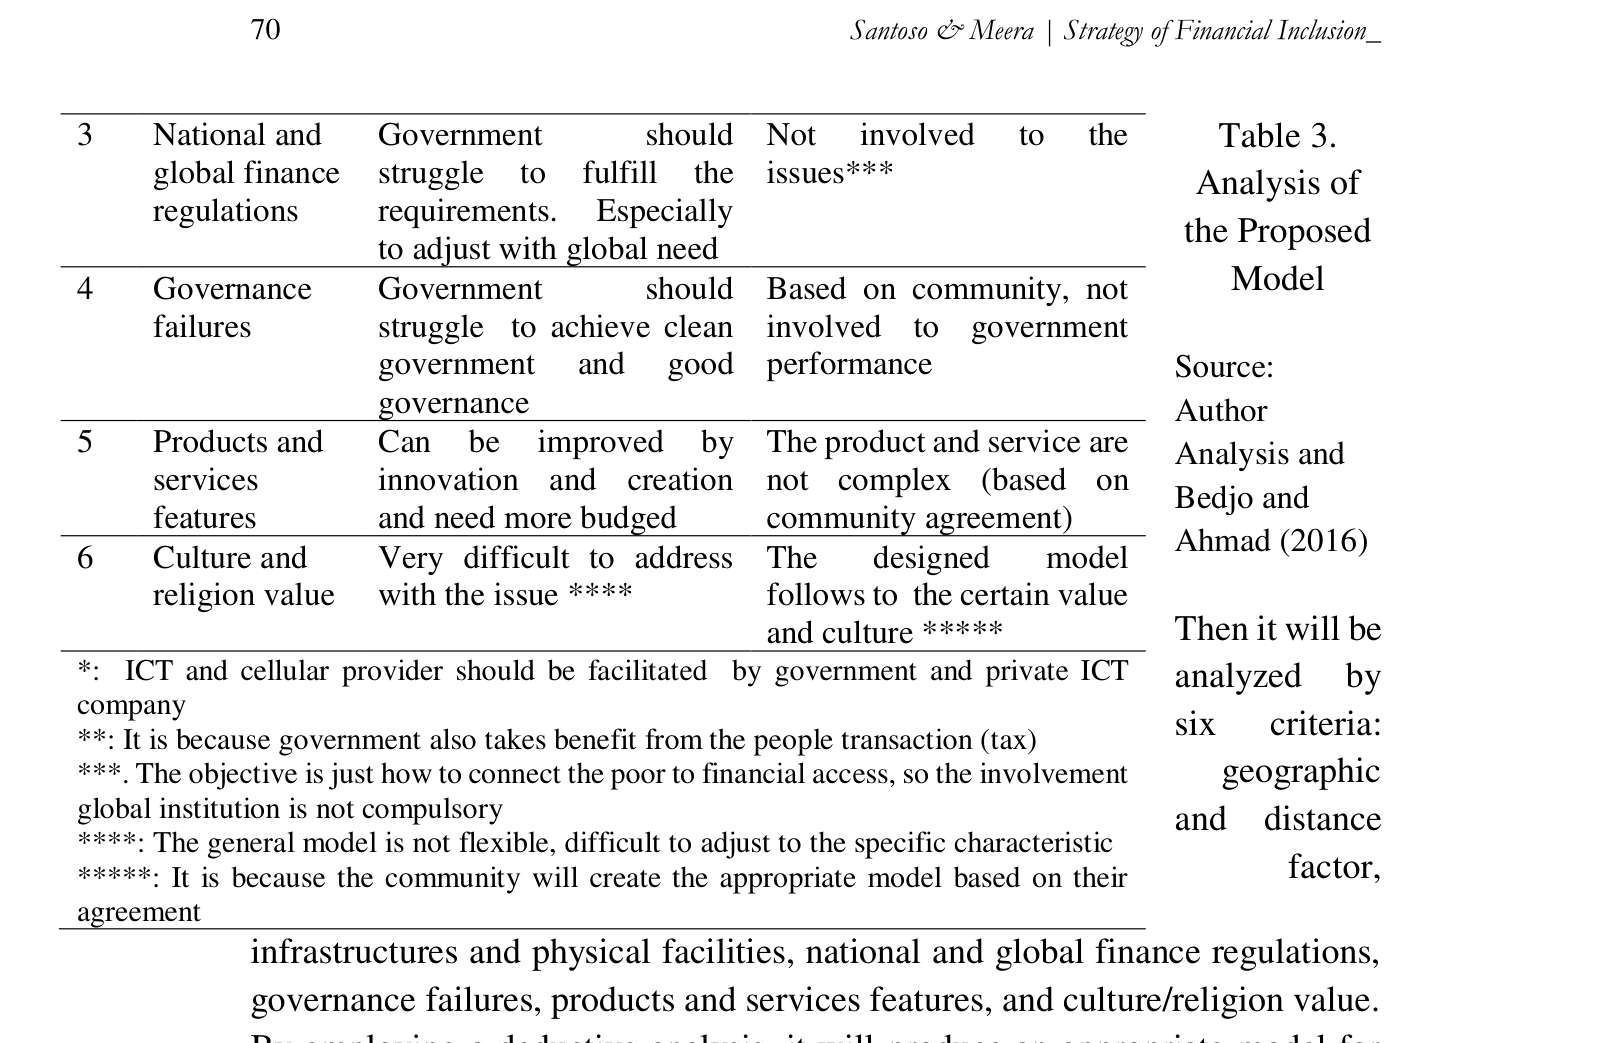
Analysis of regulations requirements. Especially the Proposed to adjust with global need
Model 4 Governance Government should Based on community, not failures struggle to achieve clean involved to government government and good performance Source:
Author 5 Products and Can be improved by The product and service are
Analysis and services innovation and creation not complex (based on
Bedjo and features and need more budged community agreement)
Ahmad (2016) 6 Culture and Very difficult to address The designed model religion value with the issue **** follows to the certain value
and culture ***** *: ICT and cellular provider should be facilitated by government and private ICT analyzed by company six criteria: **: It is because government also takes benefit from the people transaction (tax)
geographic ***. The objective is just how to connect the poor to financial access, so the involvement global institution is not compulsory and distance ****: The general model is not flexible, difficult to adjust to the specific characteristic factor, *****: It is because the community will create the appropriate model based on their agreement infrastructures and physical facilities, national and global finance regulations, governance failures, products and services features, and culture/religion value. By employing a deductive analysis, it will produce an appropriate model for Indonesian FI model. From the above analysis, it is clear that the second alternative has some superiority in term of flexibility and acceptability; however the first model also has advantage to strengthen for achieving to the global financial networking and global financial access. It is therefore, the second model cannot be ignored by just focus to the first model only.
Framework of Mobile Financial Inclusion Based on the Community
As explained previously that Indonesia is viable to implement FI covered by mobile system. By using mobile phone the system to be effective and efficient. Mobile phone nowadays is very common owned by villagers. Hence, it can accelerate the poor for accessing financial products and services. A system which efficient manner, simple procedure, and to be accessed easily is needed particularly for village people and other stakeholders. However, government involvement such financial literacy and hardware assistance to this program is crucial thing as there are some benefit taken by government if the program successful. The current mobile FI for Indonesia was offered by some researcher such Kodim, Nasrin and Sampurno (2012), Kasmiati (2013), Prasetyo (2010), Satria et al (2011) and Supartoyo, Hendriani and Kasmiati (2013). They voiced to perform FI based on mobile phone to deal with the poverty problem. However, their proposed models are still general models in nature. The important issues is being neglected such Indonesian heterogeneity in term of culture, distance, value, institutions and traditional value. It is therefore, this paper attempt to cover the research gap. By proposing an integrated model where community is considered as important element in the model.
A design framework that connecting private sectors, civil society, unbanked people, public (government) sector, information and communication technology (ICT), financial providers, agents/merchants, and banks is offered in Figure 1a and 1b.
Fig. 1.a. shows that the poor and unbanked people and other business entities can be able to access financial services such as; access customized saving, credit, financial transaction, government financial assistant and insurance services facilitated by community. It has some features in terms of connect to institutions; reduce cost of utility linkages, reduce cost of government payments, reduce bank operational cost by implement Branchless Banking concept without any hesitancies because based on consensus among community. The community system is offered based on facts as it was discussed that in Indonesia, there are so many type cultures, values, and customs. Even, some of them are willing to be financial excluded as they consider that the model is prohibited by their culture. Figure 1 described that the role of government is just coordination, supervision, and some time give assistances such as government aids, etc.
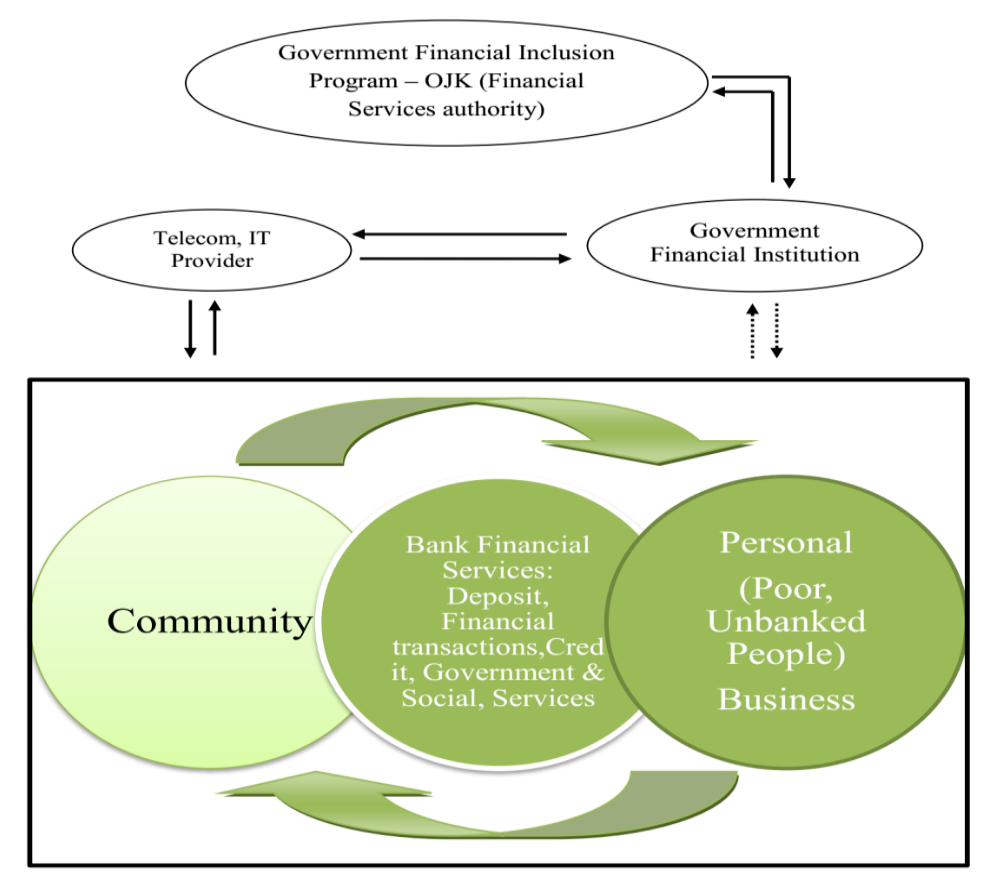
In the Figure 1, the role of government financial agency as care taker or coordination of the system by prepares the program and facilities. Besides that, government should ensure to the community members who don’t want to join FI program by reasoning value, culture, and traditional custom who still misunderstanding or not willing join to global financial program. The group such as: mass organization, custom institutions, Cooperative, Baitul Maal wa Tanwil (BMT), micro finance, financial agency and community leader. In this condition, government cannot be forced them to join to the program, however government juts take function as a mediator by introducing some financial transactions such as government & social services, and insurance, deposit, investment, etc.
Figure 2 showed that the role of government is very central and urgent, the model is top down, homogenous, similar (uniform), and based on governmental orientation. The mobile phone is used to back up any transaction that collaboration with cellular provider such as Telkomsel. XL, IM3, Indosat, etc. The weakness of the design does not give a chance to special value, cultures, customs, traditional believe, geographic distance, and special community to grow in the system. It is because the model is top down and centralistic and general model, usually the model is useful to cover educated people, developed community, and based on the city.
Figure 2. Design of Mobile Financial inclusion (Government Based) Moreover, government prepare ICT infrastructures in cooperation with the cellular providers as communication regulator by mobile phone which make possible a customers can access to financial products and services by using mobile phone. The transaction comprises B2B (business to business), P2P (personal to personal), P2B (personal to business) and B2P (business to personal). The services offered such as: money transfers, payment of bills, government to person payments, P2P transactions, B2B transactions, B2P transactions and conversely, banking services, purchasing airtime, check balances, pay electricity bills, pay for goods and services, pay school fees, view statements, receive salary, etc.
Cooperation is the important key performance indicator that ensures the implementation process to be successful. The synergy between stakeholders is needed such as central bank, government institutions, public sector, micro finance, Cooperatives, Customs tradition, Communities, ICT provider and society/business, and other agents. In this case synergy with Chiba (2009) statement that FI includes pillars: society/community-private sectors, NGOs, public leaders/public sectors, information technology, micro finance and finance literacy which related to some steps namely; approach and process, main mechanisms / instruments, implementation, and lead players. However, step by steps method is better to avoid the shock conditions, starting by educating the society, then identification for Financial Identity Number (FIN), after they have account, then, they encourage to be CIN (Customer Identity Number). By process sustain financial literacy; they are able to bankable person, then change to Debt Identity Number (DIN).
Reviews of the Proposed Model
In relation to the issue, several interviews were conducted to evaluate the proposed model. First and foremost, Meera (2013) emphasizes mobile money has several advantages such as; Increase the speed of money because of its ease of use, ease of payment / remittance, reduce transaction costs: secure, reducing the possibility of a lack of money that contributed to the recession. Moreover, this model allows the occurrence of riba in economy to be minimal. Additionally, Meera (2013) introduced that by applying information and communication technology in the transaction called the payment system of mobile and internet. It will integrate in the monetary system in terms of monetary landscape and payments and this is a monumental change in the global payment system in the form of FI to serve primarily ‘unbankable’ people. Then, the next step can be implemented integration by using commodities such as gold and silver. Gold and silver can be used as a commodity for measuring value because gold has a stable and fair value (Meera, 2013). This is a way to approach people who don’t join FI by reason Islamic values (Ibrahim & Kamri, 2017).
This is the first step to seek a riba alleviation. In addition, this is a way out to stimulate into a fair and just system. With this system, a just monetary system and a free exchange of riba, gharar, and maysir make it possible in the financial system. However, riba will be continuosly if fiat money is still inherent in the monetary system. In fact, in modern monetary systems it is actually based on fiat money, fractional reserve banking, and interest rates that trigger economic collapse (Meera and Larbani, 2009).
In addition, the government must actively involve as the private sector insufficient strength to deal the problem, the role of government especially to prepare aspects of political vision and regulation (Harjono, 2014). Some community leaders interviewed stated that poverty is usually caused by barriers to accessing capital, natural resources, human and financial resources. Therefore, to overcome the problem of poverty, it does not just FI, but need an integrated solution of both mentality and spirituality. Awalyl (2014) added that Microfinance, Cooperative has a huge role to overcome this problem, therefore Islamic microfinance such as Baitul Mal Wa Tanwil (BMT) should be placed in a central position in the movement of FI , even Indonesian Asociation BMT has established mobile FI for members. They emphasize that this model is more flexible than encouraging the national agenda; in addition, the FI’s vision in BMT is value of differences with global FI vision, in BMT encourage people to deposit or give gifts while the global FI takes out loans.
From the concept of Branchless Banking, Khalif (2014) stressed that this model is an effective way to solve the hurdles of the unbanked poor people to access financial aid. Moreover, it is able to improve their socio-economic capability. However, he stressed that the key performance indicators of successful implementation are powerfull regulations and third parties must have sufficient experience to serve customers. In addition, agents or traders must have a chain to the village so that villagers can access it easily.
Customer’s protection laws should be set to meet security and comfort issues. This is important as the transaction is done by mobile phone. In addition, educating people is also an urgent step to inform such information i.e. mechanisms, rights, procedures, and obligations. In addition, the implementation of digital FI requires a digital financial platform to link ICT (information communication technology), data sharing / mining, digital accounts, and clients using mobile phones (Khalif, 2014) and can be applied in parallel.
To ensure the success of implementation process, it is impossible to design a model for Indonesia, as Indonesia has some heterogeneity within such culture distances and value. Therefore, some model should be offered to cover these variations to ensure flexibility issues. For example, there are some Islamic organizations in Indonesia as well as traditional institutions such as Muhammadiyah, NU, Al-Wasliyah, NGO, and Tuha-Peaut-Gampoong in Aceh, Subak and Banjar in Bali, Dayak in Kalimantan, and Samin in Java. Hiring such an organization and giving them autonomous independence is a better strategy than ignoring it on the grounds of attracting public participation to participate in the program, however, the main models and standards are also important to serve the middle class and educated people (Sujak Abu, 2012; Budi, 2013; Kholil, 2012; and Dayan 2013).
Santoso (2012) argued that through the traditional institutions in the village of Gampoong, Teuha Peut in Aceh is a community-based cooperative institution, and the fraternity allows to use idle gold as a complementary currency to awaken the rural economy. Currently, the agency is still working (Damanhuri, 2013). Moreover, the institution is based on the obedience of scholars, and very effectively empower the marginalized society (Yusran, 2011). Gold and cooperative values still apply today (Abubakar, 2014).
Moreover, sociologist Damarhuri (2014) emphasizes that there are several tribes in Indonesia who will do important things in society based on their leadership and agreement, besides there are some special customs that tend to reject modern living from the west, because they have bad experiences during colonialism. Another special case in the value of Islam is that people deny financial access because it considers the reason for usury. For these varied types must be addressed with a model of FI differences. The tribes are Aceh, Bali, Dayak, Samin-Java, Bedouin and Sasak. Therefore, an ingenious approach is needed by their leaders to follow this program by offering a simpler and flexible approach and method than a common model.
Raharjo (2014) reinforces that the value of tradition must be accommodated by reason of flexibility and argument of conformity. He proposes three steps to unify specific values with national values, namely: first, accommodating these specific values can live together with global values. Second, learn the advantages and disadvantages, and finally integrate the value to the national value.
In addition, Awalyl (2014: 12) because the Islamic Microfinance Movement (BMT) states that for about 30 years BMT has an important role to empower small and micro small and medium enterprises (SMEs) with their smart strategy to serve them, and now BMT Has been widespread in 32 provinces in Indonesia. Therefore, he proposed a flexible model by granting them widespread autonomy and not asking them to join global finance with no evidence of Indonesian developments.
In contrast, global model defenders Supartoyo and Kasmiati (2013) postulated that standard models by incorporating authorized agents / merchants are indispensable. Society can be handled by agents or traders. Agents / merchants include Cooperatives, Baitul Maal wa Tanwil (BMT), microfinance, cellular operators, retail banking, personal / community leaders as well. The agent-dealer function is a mediator for bank financial transactions in collaboration with mobile service providers. The function of merchants is to serve and facilitate individuals (P) and business (B) to conduct financial transactions such as remittances, payments, deposits, government & social services, insurance and other financial transactions. He believes that the model will be able to solve problems efficiently.
IMPLICATIONS
Finally, as it was above discussed in evaluations and reviews, it can be concluded there are three scenarios of the appropriate FI model to be implemented in Indonesia, evaluations of the proposed model, namely: First, Community based FI model as such depicted in figure 3 s above, the model especially to serve the specific geographic, area, value and religions which does not deal with the national model, it is because some reasons such distances, geographic, and society. Besides that, also by reason of culture, value and specific believe in the community.
Second, the global standard model should be accommodated by adding the role of agents/merchants and commercial bank as care taker bank as shown in Supartoyo and Kasmiati (2013) model. On this model the role of agents/merchants are facilitating people for making any financial transactions. Merchants/agents could be all institutions in the society as well as community institutions such Cooperatives. This model is focused for the urban society, educated people and developed cultures and it will running together with other model.
Third, mobile payment system based on gold as measurement of value; the idea came from Meera (2013) who introduced mobile phone & internet payment systems based on gold as measurement of value. He stressed that the model increases velocity of money and reduced transaction cost. Besides that, usury in fiat money will be eradicated as gold as stable and just value. This way to facilitate people who believe that fiat money is considered does not in line with maqashid sharia, so it is not safe ways for Muslim. This model basically for serving the communities who struggle for asking back to gold as money but in the current system, it is impossible to implement gold dinar physically as it was discussed by Edawati (2013) as some obstacles such infrastructures, laws, and gold availability. Besides that, also important for certain communities which still using gold as measurement of value such Aceh (Damanhuri, 2013; Abubakar, 2014). Besides that, this system also to serve the community would adopt sharia Islam perfectly as gold as standard of measurement is important to support this action (Abubakar, 2014). It is important to note that gradual implementation is better starting by small scope. The initial step could be begun in 1st developed area and then followed by 2nd ring area etc. This is because to avoid sudden shock which may trigger uncertainties.
Moreover, those three models penting bagi pemerinah dalam develop model of FI in Indonesia. For urban area and rural area should be different model it is because the level of financial literacy. Besides that, factors should be noted before chose and implement the model, the factors are: educations level, income level, ICT literacy, acceptance values, level of cohesiveness, and religions.
CONCLUSION AND RECOMMENDATION
The conclusion of this paper are: Firstly, many literatures and research in FI especially on the FI pillars mostly just focus on the role of ICT, public sector, financial sector microfinance and financial literacy. Factor on geographies of FI, special community, institutions, and custom as alternative to the FI model is being neglected.Therefore, this research propose this issue to be considered in the FI studies and researchs.
Secondly, this research founded five the barriers of FI development, and it is assumed as the criteria to evaluate the proposed model. The barriers are: geographic and distance factor, infrastructures and physical facilities, national and global finance regulations, governance failures, products and services features, culture, traditional, and religion values.
Thirdly, to establish FI in Indonesia should consider approach; (a) the running value in the society, (b) religions believe, (c) communities willingness, (d) tradition local wisdom, and (e) culture as well. Besides that, the wide area, number of tribes, and the biggest archipelago with long distances should be considered as important factor to develop FI in Indonesia. Therefore, Community FI Model based on local value wisdom is the appropriate model as an alternative to deal with the problem by placing the community institutions as proxy for accommodating the heterogeneity value and people special characteristic in Indonesia culture. The community could be; (a) mass organization, (b) custom institutions, (c) Cooperative, (d) Baitul Maal wa Tanwil (BMT),(e) micro finance, (f) financial agency, and (g) community leader with the function as a mediator for individual-personal (P), businesses (B) who does not yet understand the modern financial program. Fourthly, the communityFI model based on local value wisdom is better if to be implemented together with the national general model to serve semi educated people, developed area, and urbanite people. Besides that, the group of people who want to adopt muamalah principles purely should be accommodated.
Fiftly, this paper propose three scenarios of the appropriate FI model to be implemented in Indonesia;(a) community based FI model, (b) standard global model FI by adopting the global model, and (c) mobile payment system based on gold as measurement of value. However, accommodating the community model in the national model will strengthen to national unity.
Sixtly, for further research could focus to develop the alternatives and criteria for developing FI model in certain area. The alternatives could be area of Indonesia which be divided into some categories such level of development or based on area then it will be evaluated by the criteria such flexibility accessibility, efficiency, and effectiveness. The respondent should be enhanced which involves scholars, academician, banking, ICT providers, NGO’s, and government by using area and stratified sampling method that can be represent Indonesian as a whole. Quantitative and qualitative method can be adopted together in order to achieve comprehensive result, besides that, focus group discussion method also important to be done, and these things is not yet carried on this research as the weakness of this study.
REFERENCES
Abubakar, Al Yasa (2014), Aceh Islamic Shariah and Islamic Finance Movement, Interview Result, on 2 December 2014, as Head of Muhammadyah of Aceh Indonesia.
Atkinson, A., Messy, F.-anne, Rabinovich, L., & Yoong, J. (2015). Financial Education for Long-term Savings and Investments. OECD Working Papers on Finance, Insurance and Private Pensions, OECD Public (39), 1-33.
Awalyl, Rizky, (2014), Peran dan Strategi BMT dalam Pemberdayaan Ummat, Paper presentation pada Sarasehan BMT Nasional, 2014, pp. 1-25, unpublished paper.
Bank Indonesia (2013a). Indonesia Motor Asia Pacific, Financial Media. Journal, V.8 No. 73 Sep 2013.
Bank Indonesia, (2013b), The Path Way of Financial Inclusion in Indonesia, Yearly Report, Dec 2013, pp.1- 12.
Bhave, Devendra, G. (2014), A Study of Development towards Financial Inclusion in India, Journal of Commerce and Management Thought, ISSN: 0975-623X, Villanova University India, 04-01-2014, 5(2), p.
229-242.
Bhanot, D., Bapat, V., & Bera, S. (2012). Studying financial inclusion in north-east India. International Journal of Bank Marketing, 30(6), 465-484.
Retrieved from
10.1108/02652321211262221\nhttp://search.ebscohost.com/logiin.as px?direct=true&db=bth&AN=79723657&site=ehost-live Blanco, Juan, et.al. (2014), Models and Barriers for Financial Inclusion, Financial Inclusion 2020- CFI, retrieved from: http://cfi-blog.org/2014/10/21/models-and-barriers-for-financial-inclusion/ on October 21, 2014, pp. 14-22.
BPS (Indonesian Centre Statistic Bureau), (2014), pp. 1-10, retrieved from:
http://www.bps.go.id/tab_sub/view.php?kat=1&tabel=1&daftar=1&i d_subyek=23%20¬ab=1, on Jan 2015.
Budi S. Tengku, (2013), Cooperation of Aceh People, Interview result, on 14 March 2013, as Aceh Scholars.
Carat, (2002), E-money, The EU Single Market. European Commission. 11 August 2013. Retrieved from http://:www.wikipedia.com.
singlemarketEC20390//onT2S, on 9 January 2014), pp. 9-23.
Chibba, M. (2008) Poverty reduction in developing countries: No consensus but plenty of solutions.World Economics 9(1): 197–210.
Chibba, M. (2009). Financial Inclusion, Poverty Reduction and the Millennium Development Goals. European Journal of Development Research, 21(2), 213-230. Retrieved from http://www.palgrave-journals.com/ejdr/journal/v21/n2/full/ejdr2008117a.html Damanhuri, (2013), Aceh People and Islamic Value, Interview Result, on 3 March 2012, as Aceh Sociologist and Scholars.
Dayan, (2013), Aceh Society and Development, Interview result, on 17 Nov 2013, as Scientist.
Demirgüç-Kunt, A., & Klapper, L. (2012). Measuring Financial Inclusion: The Global Findex Database. World Bank Policy Research Working Paper, 6025(April), 1-61. Retrieved from http://elibrary.worldbank.org/doi/book/10.1596/978-0-8213-9509-7 Dermish, Ahmed. et.al. (2011), Branchless and Mobile Banking Solutions for the Poor: A Survey, Social Science Research Network Journal-USA, SRRN-id1986316, January 23, 2011, Innovations, Vol. 6, No. 4, Fall 2011, retrieved from: http://ssrn.com/abstract=1745967, on Nov, 2014. Pp. 81-98.
Donner, J., & Tellez, C. A. (2008). Mobile banking and economic development:
linking adoption, impact, and use. Asian Journal of Communication, 18(4), 318-332.
Fuller, Duncan, Mary Mellor, Lynn Dodds and Arthur Affleck (2014), ‘Consulting the community Advancing financial inclusion in Newcastle upon Tyne, UK’, Emerald Insight International Journal of Sociology and Social Policy Northumbria University, Newcastle upon Tyne, UK, Vol. 26 Iss 5/6, Available at www.emeraldinsight.com/0144-333X.ht, link to this document, http://dx.doi.org/10.1108/01443330610674297, Downloaded on: [18 November 2014], pp. 255 – 271.
Fuller, D. (2002). Institutionalising Future Geographies of Financial Inclusion:
Antipode, (1), 85.
Edawati, Salmy, (2013), Dinar Emas; Mekanisme Implementasi dalam Ekonomi Semasa, Ph.D Thesis, UKM-Malaysia, pp. 1-338.
Gerai Info (2011), Bank Indonesia (Central Bank) News Letter, Edisi XV, TH 2, Juni 2011, email : [email protected], website : www.bi.go.id, pp.
1-8.
Hadad, M. (2010), Perluasan Akses Perbankan; Bagi Penggerak Roda Perekonomian, Gemari Magazine, Edisi; 118/XI, Nov 2010, pp1-89.
Harjono S, (2014), BMT; Islamic Financial Inclusion Vision-Mission, Interview result, on 10 December 2014, as PB-BMT Association Jakarta activist.
Hernandez, Janet, Jeff Bernstein, and Amy Zirkle, (2011), THE REGULATORY LANDSCAPE FOR MOBILE BANKING, Telecommunications Management Group (TMG), Inc. International Telecommunication Union (ITU), GSR 2011 Discussion Paper, pp. 1-25, email from: [email protected].
Ibrahim, A., & Fitria. (2012). Implikasi Penetapan Margin Keuntungan pada Pembiayaan Murabahah (Suatu Studi dari Perspektif Islam Pada Baitul Qiradh Amanah). Share: Jurnal Ekonomi dan Keuangan Islam, 1(2), 142-162.
Ibrahim, A., & Kamri, N. A. (2017). The Ethical Practices of Islamic Banking:
An Analysis from Customer Satisfaction Perspective. MIQOT: Jurnal Ilmu-ilmu Keislaman, 41(1).
Ghosh, J. (2013). Microfinance and the challenge of financial inclusion for development. Cambridge Journal of Economics, 37(6), 1203-1219.
Kaddu, Michael. (2014), Banking on Change: Breaking the Barriers to Financial Inclusion, NPM Platform for inclusive Finance, Head of Corporate Affairs, Barclays Bank Uganda, Nov 2014. pp.74 Karlan, D. and Zinman, J. (2007) Expanding Credit Access: Using Randomized Supply Decisions to Estimate the Impacts. Washington DC: Centre for Global Development. Unpublished Working Paper no.108. pp. 21-34 Khalif R. (2014), The Viability of Financial Inclusion from ICT Aspects, Interview result, on 10 November 2014, As IT Consultant/Builder.
Kartiko (2013), Strategic of Islamic Micro Finance (BMT) in Financial Inclusion Movement, Interview Result, on 12 July 2014, as Chief of Java-BMT Association.
Kholil, (2012), Participation Level of Aceh Society for Development, Interview Result, on 14 July 2012, as The Leader of Aceh NGO’s.
Kodim, Nasrin and Sampurno (2012). Membangun Masyarakat Perdesaan yang Sehat Produktif.Perdesaan dalam Rangka Peningkatan, Kesejahteraan Masyarakat Pemikiran Guru Besar Perguruan Tinggi Badan Hukum Milik Negara. IPB Press, Bogor, Unpublished paper, pp. 1-25.
Madhur, Jha, Samantha. Amerasinghe, John, Calverley. (2014), Special Report Financial Inclusion: Reaching the unbanked, 4 September 2014, Standard Chartered Bank, Canada, 2014, pp. 24-32.
Moorthiet et al. (2013), Bracnhless Banking by Corporation Bank – A Branding Perspective. Retrieved from http://tejas.iimb.ac.in/articles/10 accessed on 26th July 2013 Gonville, M. Baddeley (2004), Using e-cash in the new economy: An economic analysis of micropayment systems, Caius College and Faculty of Economics and Politics, Cambridge, UK, [email protected], Journal of Electronic Commerce Research, VOL. 5, NO.4, 2004, pp. 239-258 McKinsey (2008), Cross-country variation in household access to financial services, research conducted in partnership with the Financial Access Initiative (a consortium of researchers at New York University, Harvard, Yale, and Innovations for Poverty Action); we relied on financial usage data from Patrick Honohan, Journal of Banking & Finance, Volume 32, Number 11, 2008, pp. 493–500 McKinsey, (2010), Global Financial Inclusion: Achieving full financial inclusion at the intersection of social benefit and economic sustainability, pp.1-44, Retrieved from:
http://www.thegiin.org/binary-
data/RESOURCE/download_file/000/000/149-1.pdf, On 12 March 2014.
Meera, (2013), Islamic Finance and Its Role in Economic Development, Presentation on International Seminar, UGM, Yogyakarta, 12 November 2013, pp. 1-23 Meera and Larbani, 2009, “Ownership Effects of Fractional Reserve Banking:
An Islamic Perspective,” in Humanomics, vol. 25, no. 2 (May 2009), 101-116. See also Ahamed Kameel Mydin Meera and Moussa Larbani, “Seigniorage of Fiat Money and the Maqasid al-Shariʿah: The Unattainableness of the Shariʿah,” in Humanomics, vol. 22, no. 1 (2006); and idem, “Seigniorage of Fiat Money and the Maqasid al-Shariʿah: The Compatibility of the Gold Dinar with the Maqasid,” in Humanomics, vol. 22, no. 2 (2006).
Mihasonirina Andrianaivo, (2012) Mobile Phones, Financial Inclusion, and Growth, Review of Economics and Institutions Vol. 3, University of Perugia 2012, pp. 19-31.
Mulya, E, S, (2012), Wujudkan Wujudkan Financial Inclusion Melalui Edukasi dan Perluas Jangkauan’, p.1-4, Swa Magazine. Retrieved from:
http://swa.co.id/business-strategy/wujudkan-financial-inclusion-melalui-edukasi-dan-perluas-jangkauan, on 9 Feb 2014.
Nasution Darmin, (2010), Welcoming Remark at the 2010 AFI Global Policy Forum Bali, 27 Sept 2010, retrieved from AFI web on 12 May 2013, pp. 1-7.
NFER. (1992) Financial Literacy. London: National Foundation for Educational Resources (NFER).
Prasetyo, Dedy (2010), Branchless Banking; Satu Pilar Mencapai Keuangan Inklusif. Crestpent Press, Bogor Raharjo Trisno (2014), Indonesian Values, Customs, and Traditional Institutions, Interview Result, on 2 December 2014, as Senior Indonesian Sociologist.
Radcliffe, Dan and Voorhies Rodger, (2012), A Digital pathway to Financial Inclusion, Presented paper, electronic copy available at:
http://ssrn.com/abstract=2186926.pp. 1-16.
Rofah S., 2012, Islamic Finance Development, Interview result, on 9 Feb, 2012, as Expert Islamic Law.
Sankaramuthukumar, S and Alamelu, K (2012), Financial Inclusion: African Scenario, Insight on Africa Journal, Sage UK: London, England SAGE Publications 07-01-2012, 4(2), ISSN: 0975-0878, pp. 121-135.
Santoso, Bedjo, (2012), Complementary Currency Model Based on Idle Physical Gold in ACEH, Conference Proceeding of Islamic Economic Economics and Finance (CMIEF 2012), University Kebangsaan Mayasia (UKM), 5th -6th November 2012. Pp. 54-69 Santoso, Bedjo and Khaliq Ahmad (2016), Islamic Microfinance Branchless Banking Model in Indonesia, Intellectual Discourse, Special Issue (2016) 409–433, Copyright © IIUM Press, ISSN 0128-4878 (Print);
ISSN 2289-5639 (Online).
Satria, Arif et al. (2011). Menuju Desa 2030. Crestpent Press: Bogor, Working paper, p.1-23 Shankar, S. (2013). Financial Inclusion in India: Do Microfinance Institutions Address Access Barriers? Financial Inclusion: Importance and Common Barriers. ACRN Journal of Entrepreneursip Perspectives, 2(1), 60-74., Feb. 2013.
Sujak, Abu, (2012), Muhammadyah Concept of Society Empowerments, Interview Result, on 1 July 2012, as Deputy Chief of Aceh – Muhammadyah, on 13 March 2012.
Swadiyanti, S, (2011), Nomor Unik Menju Masyarakat Sadar Perbankan, Gerai Info (2011), Bank Indonesia (Central Bank) News Letter, Edisi XV, TH 2, Juni 2011, email : [email protected], website : www.bi.go.id, pp.
1-8
Tempo Magazine, (2014), edition: Selasa, 13 Mei 2014, retrieved from:
http://www.tempo.co/read/kolom/2014/05/13/1340/Miskin-Rentan-dan-Timpang, on (12 Dec 2014). p.1 Supartoyo, Yesi Hendriani and Yesi Kasmiati, (2013) Branchless Banking Mewujudkan Keuangan Inklusif sebagai Alternatif Solusi Inovatif Menanggulangi Kemiskinan: Review dan rekomendasi, Program Magister Sekolah Pascasarjana Institut Pertanian Bogor, unpublished paper, IPB Press, Bogor, pp.78-82.
Yusran, (2011), Islamic Value in Aceh, Interview Result, on: 11 July 2011, as Scientist.
Ibrahim, A., & Fitria. (2012). Implikasi Penetapan Margin Keuntungan pada Pembiayaan Murabahah (Suatu Studi dari Perspektif Islam Pada Baitul Qiradh Amanah). Share: Jurnal Ekonomi dan Keuangan Islam, 1(2), 142-162.
Ibrahim, A., & Kamri, N. A. (2017). The Ethical Practices of Islamic Banking: An Analysis from Customer Satisfaction Perspective. MIQOT: Jurnal Ilmu-ilmu Keislaman, 41(1).
Notes
diusulkan. Hasilnya ditawarkan dalam tiga skenario; model yang sesuai berbasis masyarakat, kemudian model standar global inklusi keuangan, dan akhirnya, sistem pembayaran mobile berbasis emas sebagai pengukuran nilai. Dengan mengakomodasi model masyarakat yang diimplementasikan bersama-sama dengan dua model akan memperkuat persatuan nasional. Kata kunci: Inklusi Keuangan, Orang yang tak memiliki rekening bank, Komunitas, Mobile Sistem, Nilai-